Getting a mortgage in Japan for foreigners comes down to one thing: residency status. Permanent residents borrow almost like locals. Non-PR residents can qualify at some banks with bigger down payments. Meanwhile, non-residents abroad usually can’t get a loan at all.
Why Ownership and Financing Aren't the Same Thing
A lot of people thinking about investing in a property in Japan mix up two questions. Can a foreigner own property in Japan? And will a bank actually lend them the money to buy it? The first answer is simple: yes, always has been. Japan doesn’t ask about your passport or your visa status before letting you hold title to land or a building. You sign the same contract a Japanese buyer signs, register the same way, and end up with the same legal rights.
The second question is where most foreign buyers get stuck. Financing comes down to whatever a particular bank decides, and every bank sets its own bar for how much risk they’re willing to accept. If a bank turns you down, that has nothing to do with your right to own the place. It just means that the bank doesn’t feel comfortable lending across borders, in a currency and a legal system they don’t deal with every day.
Again, you’re never legally blocked from buying, but you might be blocked from certain loan products depending on your visa.
The Residency Ladder: How Your Visa Status Decides Your Loan Options
Japan’s mortgage market splits along a residency line. Permanent residents and special permanent residents sit at the top. If that’s you, banks treat you almost the same as a Japanese citizen. You can walk into MUFG, Mizuho, SMBC, Resona, pretty much any major domestic bank, and qualify for a wide range of products out there, including the government-backed Flat 35 program.
One rung down are foreign residents in Japan on a work visa, spouse visa, or something similar, without PR. If you’ve got a valid zairyu card and Japanese income, you can still get into a decent slice of the mainstream market. A handful of banks have built loan products just for this group, though the list of willing lenders shrinks fast and the terms get tighter.
Then there’s the non-residents living entirely outside Japan. If you have no residence card and no Japanese address, standard mortgages are basically off the table. It doesn’t matter how good your income is or how strong your credit history is back home.
If your spouse is a Japanese citizen or a permanent resident, most of the big banks will lend if your spouse applies as the main borrower or co-signs with you, often on close to citizen terms.
Inside the Application: What a Japanese Bank Actually Checks
Japanese lenders check foreign applicants against a consistent set of boxes.
Income stability comes first. Banks want a track record, not just what you’re earning right now, and for foreign applicants that bar sits higher than it does for citizens. The reasoning is simple: a bank handing out a thirty-five-year loan wants proof your income will hold up, and a short job history just doesn’t give them much to go on.
Debt-to-income ratio matters too. Credit card balances, car loans, whatever debt you’re carrying, it all gets factored in, and if your credit history lives entirely outside Japan, that can be harder to document than a bank would like. Some lenders also care about your Japanese ability, since a borrower who can read and respond to loan paperwork directly is just less of a hassle for them.
If you do qualify for a loan, you should also accept beforehand that approval takes a while, and getting a straight answer out of a branch can take a very long time. Build slack into your timeline, because this is not going to be a same-week process.
Buying Without Setting Foot in Japan With a Power of Attorney
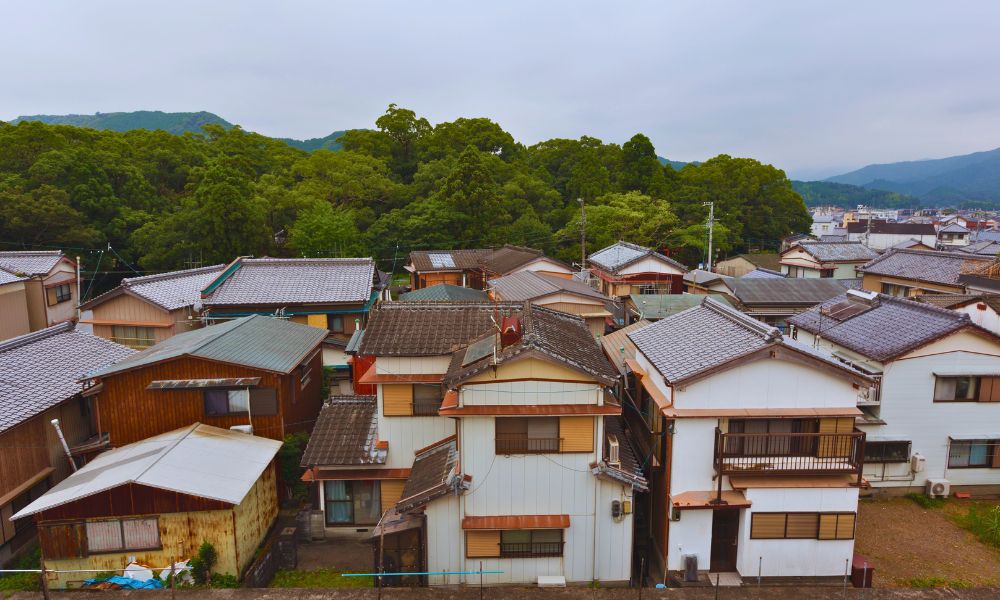
For foreigners, financing isn’t the only path though. Prices outside the major cities run low enough that a full cash purchase is realistic for a lot of overseas buyers, something that would be out of reach back home in a market like London, Sydney, or San Francisco.
Paying cash skips the entire residency-and-lending bottleneck covered above. No bank underwriting to satisfy, no down payment threshold to hit. It also builds a documented asset in Japan that can strengthen a future loan application down the line, particularly for buyers working toward permanent residency or building up rental income that shows real cash flow.
Cash or financed, most of this process doesn’t require being in Japan at all. The tool that makes it work is a notarized power of attorney. You give a representative, usually your agent or a Judicial Scrivener (shiho shoshi), the authority to sign for you at the property registry and at closing. Your identity gets verified remotely, the funds get wired and confirmed, and your representative handles the transfer and registers the title in your name.
Remote buying isn’t some gray area. It’s actually how a good chunk of foreign buyers do this every year.
Mortgage in Japan for Foreigners FAQs
Can a foreigner buy property in Japan without a visa?
Yes. Japan doesn’t require citizenship, residency, or a visa to buy property. Your immigration status and your property ownership run through completely separate systems.
Can I get a Japanese mortgage on a work visa without permanent residency?
Yes, though your options shrink fast. A small group of lenders work with applicants on a valid work visa without PR, but expect a bigger down payment, and a higher rate than a permanent resident gets.
Does marrying a Japanese citizen change my mortgage eligibility?
If your spouse holds Japanese citizenship or PR and applies as the main borrower or co-signs with you, most of the big domestic banks will lend on terms close to what a citizen gets alone.
Buy a House in Japan Remotely with Sumica
Everything covered here is something you could technically handle solo. You shouldn’t, though, not from another country and not in a second language.
That’s the gap Sumica fills. We source off-market properties through a private network and screen every option for budget and yield before it ever reaches you. We even handle renovation through local craftspeople we trust, with photo and video updates at every stage, and fixed-price packages that keep your budget from moving on you.
Once the property’s ready, our property management team can also handle tenants, contracts, rent collection, and maintenance directly, with monthly reports sent wherever you happen to be.
We’ve handled over 1,100 projects, and we have an accommodating bilingual team you can easily reach on WhatsApp. Contact Sumica now.